Ithaca Energy plc (LON:ITH) has announced that it has entered into an agreement with Suncor Energy Inc. to acquire a portfolio of conventional offshore oil assets located in shallow waters off the East Coast of Newfoundland and Labrador, Canada, for upfront cash consideration of US$860 million, plus potential oil price related contingent consideration of up to US$250 million based on a sharing factor of 50%.
The assets comprise a 48% operated working interest in Terra Nova, a 40% non-operated interest in the White Rose Existing Lands, and a 38.6% non-operated interest in the White Rose Growth Lands, including the West White Rose Extension.
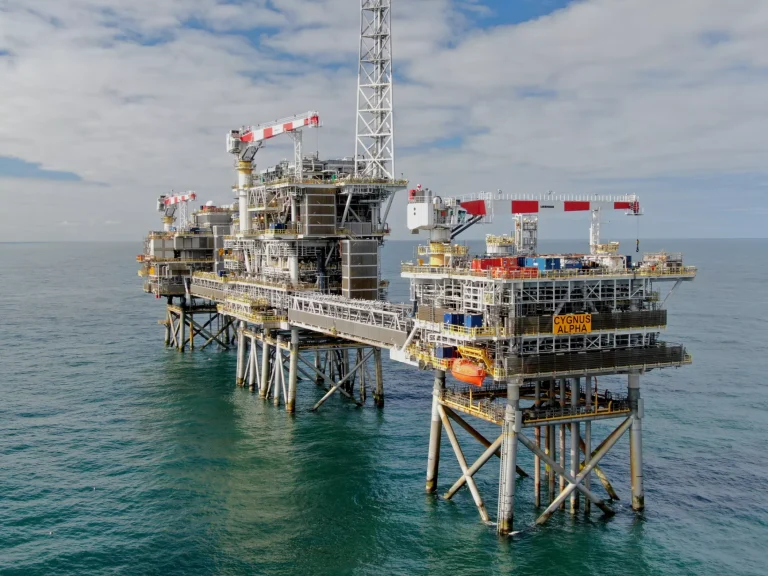
Terra Nova is a producing, operated shallow-water oil asset supported by a recently completed Floating Production Storage and Offloading asset life extension project. White Rose is operated by Cenovus Energy Inc. and has high-margins and substantial near-term production growth expected from West White Rose, where first production is anticipated in Q4 2026.
Yaniv Friedman, Executive Chairman of Ithaca Energy, commented “This acquisition marks the next era of growth for Ithaca Energy as we make our inaugural international acquisition in Offshore East Coast Canada. The Transaction delivers on our clear stated growth strategy as we seek to diversify and grow our production and resource base and replicate our success in the United Kingdom Continental Shelf (“UKCS”) through disciplined international expansion in regions we believe we can create long-term value for our shareholders.”
“The Transaction builds on our vision for ‘Scale, Stability and Strength’. It adds long-life, low-decline barrels in an offshore operating environment similar to the UKCS, which will materially enhance our medium-term production outlook and create a platform for further organic growth and consolidation, while expected to deliver immediate cash flow and dividend accretion.”
“We are excited to welcome an experienced operating team with deep regional expertise and to build on the strong operating history of these assets.”
Key Transaction Highlights
The Transaction is fully aligned with the Group’s inorganic growth strategy, delivering value accretive M&A, while meeting all of the Group’s strategic investment parameters.
- Transformational strategic basin entry into Offshore East Coast Canada
- Execution of international expansion strategy enhances portfolio scale, diversification and exposure to premium Northern OECD barrels
- Disciplined and transformational entry into a well-understood basin, with many similar characteristics to UKCS
- Attractive fiscal and regulatory regime with pragmatic federal and provincial government, providing strong support for further investment and development in the basin
- High-quality, low-decline assets in well-understood basin
- Shallow water, long-life conventional oil assets with significant operating history, located in a well- developed, low-complexity operating environment
- Basin similarities play to Ithaca Energy’s expertise and capabilities, including operating FPSOs
- Long-life assets with 2P reserves life of ~17 years and estimated five-year average 2P production expected to be ~30 kboe/d over 2027-31[1]
- Material recent investment across the portfolio, including FPSO refurbishments, provides solid foundation for next phase of field development
- Established and experienced operating team
- Secures access to high-calibre operatorship credentials upon basin entry, with proven track record of delivering safe, environmentally responsible and efficient operations in Offshore East Coast of Canada
- Extensive history of and expertise in exploration, development, production and optimisation across portfolio of operated and non-operated assets
- Maintains established relationships with leading blue-chip partners critical to ongoing success in the basin
- Material organic and inorganic growth potential
Offers further organic growth optionality:
- 2P Production expected to grow to 35-40 kboe/d by 2029[1], driven by near-term production growth from West White Rose development, with first production anticipated in Q4 2026
- Acquisition supports upgrade of Ithaca Energy’s medium-term production outlook to between 140 – 150 kboe/d1,[2]
- Adds material 2P reserves of 103 mmboe1, diversifying the Group’s reserves base, with substantial additional remaining resource volumes of c.200 mmboe1 providing further investment optionality with significant resources advancing towards Final Investment Decision (“FID”)
- Material organic growth potential from infill drilling, near-field step-out opportunities and exploration exposure
Establishes platform for further M&A:
- Acquisition positions Group as the 5th largest operator in Offshore Canada by production, establishing a strong platform in the region
- Creates credible platform for further inorganic growth in North America, as the Group continues to seek scale
- Continued active but disciplined screening of inorganic growth opportunities, with focus on adding premium northern-OECD barrels
- Expected to be immediately cash flow and dividend accretive
- Acquisition to be financed via a combination of cash in hand, utilisation of the Group’s existing borrowing base facility and secured financing in country. Deal contingent hedging executed to protect transaction value and future cash flows at current market pricing
- Portfolio offers brent-linked pricing assets, with limited future base capex following a period of material investment in the Assets, increasing efficiency and lower operating costs and an attractive corporate tax rate
- Expected to be immediately accretive to Adjusted EBITDAX (as defined below), free cash flow and dividend per share from Completion
- Increased cash flow generation and modest leverage position post-acquisition, sitting considerably below the Group’s capital allocation framework ceiling, supports near-term deleveraging and enhanced and sustainable shareholder returns
Transaction Consideration and Financing
The base consideration for the Transaction is US$860 million in cash payable on completion of the Transaction, subject to customary adjustments based on an economic effective date of 1 July 2026. The Group expects to fully finance the Transaction through cash in hand, utilisation of its borrowing base facility and secured in country financing. In addition, the Group may pay Suncor up to an additional US$250 million of contingent consideration linked to Brent crude oil prices over a 27-month period commencing 1 July 2026, which would be funded from Ithaca Energy’s free cash flow.
Transaction Completion and Timing
Completion is targeted for H1 2027, subject to satisfaction of customary closing conditions, including applicable regulatory and government approvals in Canada.
Board Approval
The board of directors of Ithaca Energy believes that the Transaction is in the best interests of the Company and its shareholders as a whole and has approved the Company’s entry into the Acquisition Agreement.